2026 Qualified Charitable Distributions for Military Retirees
Oct 30, 2026 | 4 min. read
Learn how qualified charitable distributions work, what the 2026 limits are and how they may fit into retirement-income and charitable-giving planning.
If charitable giving is part of your financial plan, a qualified charitable distribution (QCD) may help you support causes you value while managing retirement income. IRA owners age 70½ or older may be able to transfer money directly from an eligible IRA to a qualified charity through a QCD.
What Is a Qualified Charitable Distribution?
A QCD is a direct payment from an eligible IRA to an eligible charitable organization. Traditional IRAs and certain inherited IRAs may qualify. SEP and SIMPLE IRAs may qualify in years when the employer does not make a contribution. When requirements are met, a QCD may count toward an IRA owner’s required minimum distribution (RMD) without being included in regular taxable income.
How Do Qualified Charitable Distributions Work for Military Retirees?
A QCD must be paid directly from an eligible IRA to an eligible charitable organization. For military retirees, this can require extra planning when much of their retirement savings is held in the Thrift Savings Plan (TSP). If the distribution is paid to you first and you later donate the money, it generally will not qualify. You also cannot receive goods, services or another benefit in exchange.
The receiving organization must be eligible to receive QCDs. Donor-advised funds, private foundations and certain supporting organizations generally are not eligible. The IRA owner must also be age 70½ or older on the date of the distribution.
Can I Make a QCD Directly From My TSP Account?
QCDs cannot be made directly from the TSP. Military retirees need eligible IRA assets to make a QCD. Moving assets from the TSP to an IRA is a separate planning decision that may involve differences in costs, investment choices, withdrawal options, creditor protections and account services. Consider those factors with your Financial Advisor and a qualified tax professional before moving money solely to make a QCD.
Qualified Charitable Distribution 2026 Updates
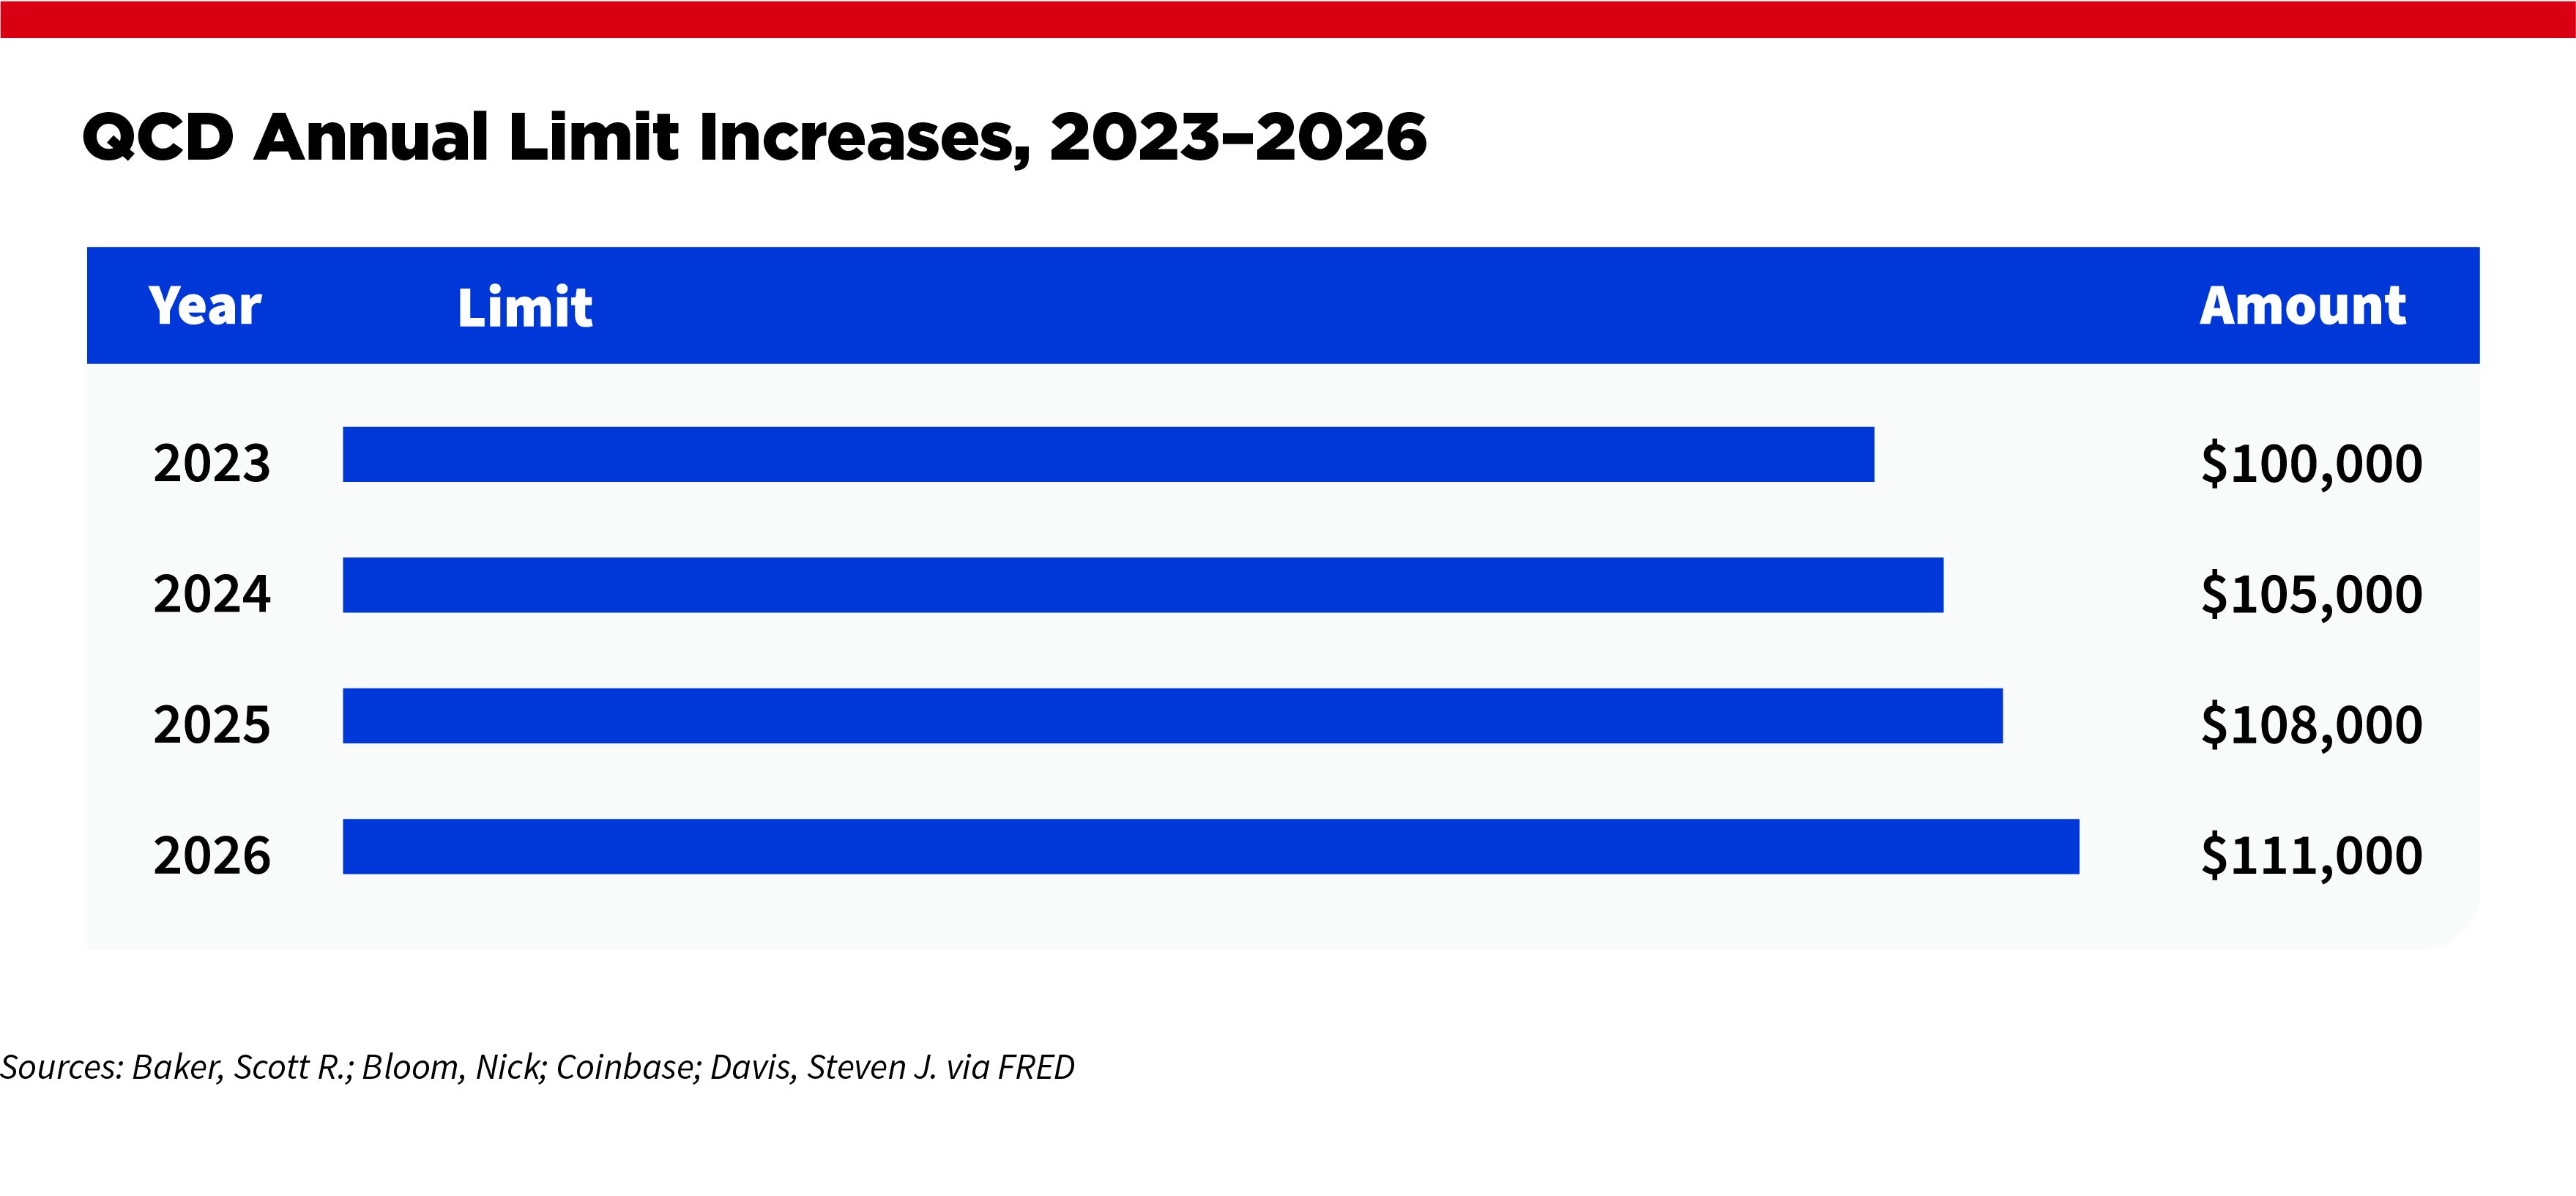
Annual QCD limits are adjusted for inflation. The following limits apply for 2026:
2026 QCD Annual Limit
For 2026, eligible IRA owners age 70½ or older may make up to $111,000 in QCDs. The limit applies per eligible IRA owner, not per account. For married couples, each eligible spouse may make QCDs up to the annual limit from their own eligible IRA. A QCD may count toward all or part of the IRA owner’s RMD for the year.
Increase in QCD Gift Annuity Limit in 2026
For 2026, an eligible IRA owner may also make a one-time QCD election of up to $55,000 to certain qualifying split-interest entities — arrangements that share income and assets between charitable organizations and private individuals — including some charitable gift annuities. Restrictions apply, including rules for the receiving entity, beneficiaries and distributions. Review this option with qualified tax, legal and financial professionals before proceeding.
How Do I Request a Qualified Charitable Distribution?
QCD procedures vary by IRA custodian and charity. Before requesting a distribution:
- Confirm the charity is eligible to receive QCDs and verify its legal name, mailing address and payment instructions.
- Follow your IRA custodian’s procedures and make sure payment is payable to the charity, not to you.
- Keep written acknowledgment from the charity documenting the amount received and whether goods or services were provided.
To count for the current tax year, a QCD generally must be completed by Dec. 31. Ask your custodian about processing deadlines early, especially if you are making a year-end transfer.
QCD Advantages for Military Families
For military families, a QCD can be more than a charitable-giving tool. When used as part of a broader retirement-income strategy, it may help manage taxable income, support causes connected to the military community, and simplify giving from eligible IRA assets.
Managing the Military Retirement Tax Stack
Military retirees often receive income from several sources, such as retired pay, Social Security, pensions and required minimum distributions (RMDs). A QCD can count toward some or all of an IRA RMD without adding that amount to adjusted gross income, as long as the requirements are met. The tax impact will depend on the retiree’s overall financial situation.
Potential Impact on Medicare Surcharges (IRMAA)
Because an eligible QCD is generally excluded from adjusted gross income, it may affect the income used to determine future Medicare IRMAA surcharges. Medicare generally relies on tax-return information from an earlier year, and a QCD may not change the surcharge in every situation. Review timing with a qualified tax professional.
Direct Support for Military and Veteran Causes
Some military relief societies, veterans organizations and military family support organizations may be eligible to receive QCDs. Confirm eligibility before requesting the transfer because donor-advised funds, private foundations and certain supporting organizations generally do not qualify.
Tax Implications of Qualified Charitable Distributions
Unlike a regular IRA withdrawal, a QCD excludes the donated amount from taxable income when requirements are met. Your IRA custodian will generally report the distribution on Form 1099-R but may not identify it as a QCD.
When filing your federal income tax return, you generally report the total IRA distribution and taxable portion on the applicable Form 1040 lines and enter “QCD” as directed. The tax effect may depend on whether you itemize deductions and other individual circumstances, so review the transaction with a qualified tax professional.
An IRA distribution generally will not qualify as a QCD if:
- The distribution check is made payable to you rather than the charity.
- You are younger than age 70½ on the date of the distribution.
A qualified charitable distribution may be worth considering if charitable giving is part of your financial plan and you meet the eligibility requirements. Discuss the strategy with your Financial Advisor and a qualified tax professional before taking action. Your First Command Financial Advisor can help you decide whether a QCD fits your charitable-giving and retirement-income strategy.
Qualified Charitable Distributions FAQ
Q: Are qualified charitable distributions reported on Form 1099-R?
A: Your IRA custodian generally issues Form 1099-R reporting the distribution, but it may not separately identify the amount as a QCD.
Q: Can you make a qualified charitable distribution from a 401(k)?
A: No. A QCD cannot be made directly from a 401(k), TSP or another employer retirement plan. Eligible assets may sometimes be moved to an IRA, but a rollover is a separate planning decision with costs, tax considerations and other tradeoffs.
Q: Are churches or religious institutions eligible for qualified charitable distributions?
A: Many religious institutions are eligible, but confirm eligibility and payment instructions before requesting the transfer.
TSP funds have very low administrative and investment expenses, and low expenses can have a positive effect on the rate of return of your investment.
Prior to requesting a rollover from your Thrift Savings Plan (TSP) account to an Individual Retirement Account (IRA), you should consider whether the rollover is suitable for you. There may be important differences in features, costs, services, withdrawal options and other important aspects between your TSP account and IRA.
First Command and its affiliates do not provide legal or tax advice. This material is for informational purposes only and should not be relied on for legal or tax advice. You should consult your own legal or tax advisors before engaging in any transaction.
Get Squared Away®
Let’s start with your financial plan.
Answer just a few simple questions and — If we determine that you can benefit from working with us — we’ll put you in touch with a First Command Advisor to create your personalized financial plan. There’s no obligation, and no cost for active duty military service members and their immediate families.